A poor monthly budget often fails because it describes ideal spending instead of actual spending. Categories may look sensible on paper while ignoring irregular bills, small repeated purchases, seasonal costs, or the real amount a household spends on food and transportation.
A useful budget begins with evidence. Review what happened to your money before deciding what should happen next month.
Build Categories From Recent Transactions
Start with bank, card, and cash spending from several recent months. Group transactions into practical categories such as housing, groceries, transportation, debt payments, health costs, subscriptions, eating out, personal spending, and savings.
The Consumer Financial Protection Bureau recommends examining real spending patterns and accounting for less-frequent expenses rather than editing the numbers to match what you think you should spend.
People comparing different personal reading resources may find many budgeting systems, but no preset category percentage can replace an accurate picture of their own expenses.
Separate Fixed, Flexible, and Irregular Costs
Some expenses remain fairly predictable. Rent, insurance premiums, loan payments, and certain subscriptions may change little from month to month.
Others move constantly. Groceries, fuel, entertainment, electricity, repairs, gifts, and medical costs can fluctuate enough to break a budget that assumes every month will look identical.
General online commentary and ideas may present simple budget formulas, but those formulas should be treated as starting points rather than financial rules.
| Expense Type | Typical Example | Budget Approach |
|---|---|---|
| Fixed | Rent or loan payment | Plan exact amount |
| Flexible | Food or fuel | Use realistic range |
| Irregular | Repairs or gifts | Set aside monthly |
| Optional | Entertainment | Adjust when needed |
Create Space for Non-Monthly Bills
A budget can appear successful for several months and then collapse when annual insurance, vehicle maintenance, school costs, holidays, or home repairs arrive.
Estimate predictable irregular expenses and divide them across the months leading up to payment. Keeping money reserved for these costs can reduce the temptation to treat every irregular bill as an emergency.
Broader household planning material can encourage useful organization, but financial decisions should still reflect your income, obligations, debt, savings goals, and risk tolerance.
Compare the Plan With the Actual Month
At month’s end, don’t judge the budget only by whether you stayed under every category. Look at where the assumptions were wrong.
If groceries consistently exceed the planned amount while entertainment stays well below its limit, the categories may need adjustment. A good budget should become more accurate as you collect more information.
Adjust Without Hiding Overspending
Moving money between categories is reasonable. Pretending repeated overspending is a one-time exception is not.
If one category repeatedly consumes more income than expected, decide whether the amount is necessary, reducible, or being underestimated. That distinction matters more than preserving an arbitrary target.
Why Extremely Strict Budgets Often Fail
Cutting every flexible category to the smallest possible number can make a spreadsheet balance while creating a plan that’s difficult to follow. Budgets also fail when they omit occasional costs or assume future discipline will erase established spending patterns overnight.
Another mistake is treating savings as whatever remains at the end. Depending on your circumstances, planning a realistic savings amount in advance may make the goal easier to track.
The purpose isn’t perfection. It’s creating a plan you can actually use.
When Outside Financial Help May Be Useful
Consider qualified financial guidance if debt payments have become difficult to manage, you’re regularly unable to cover essential expenses, you’re considering major debt-relief decisions, or your financial situation involves complicated tax, legal, investment, or retirement questions.
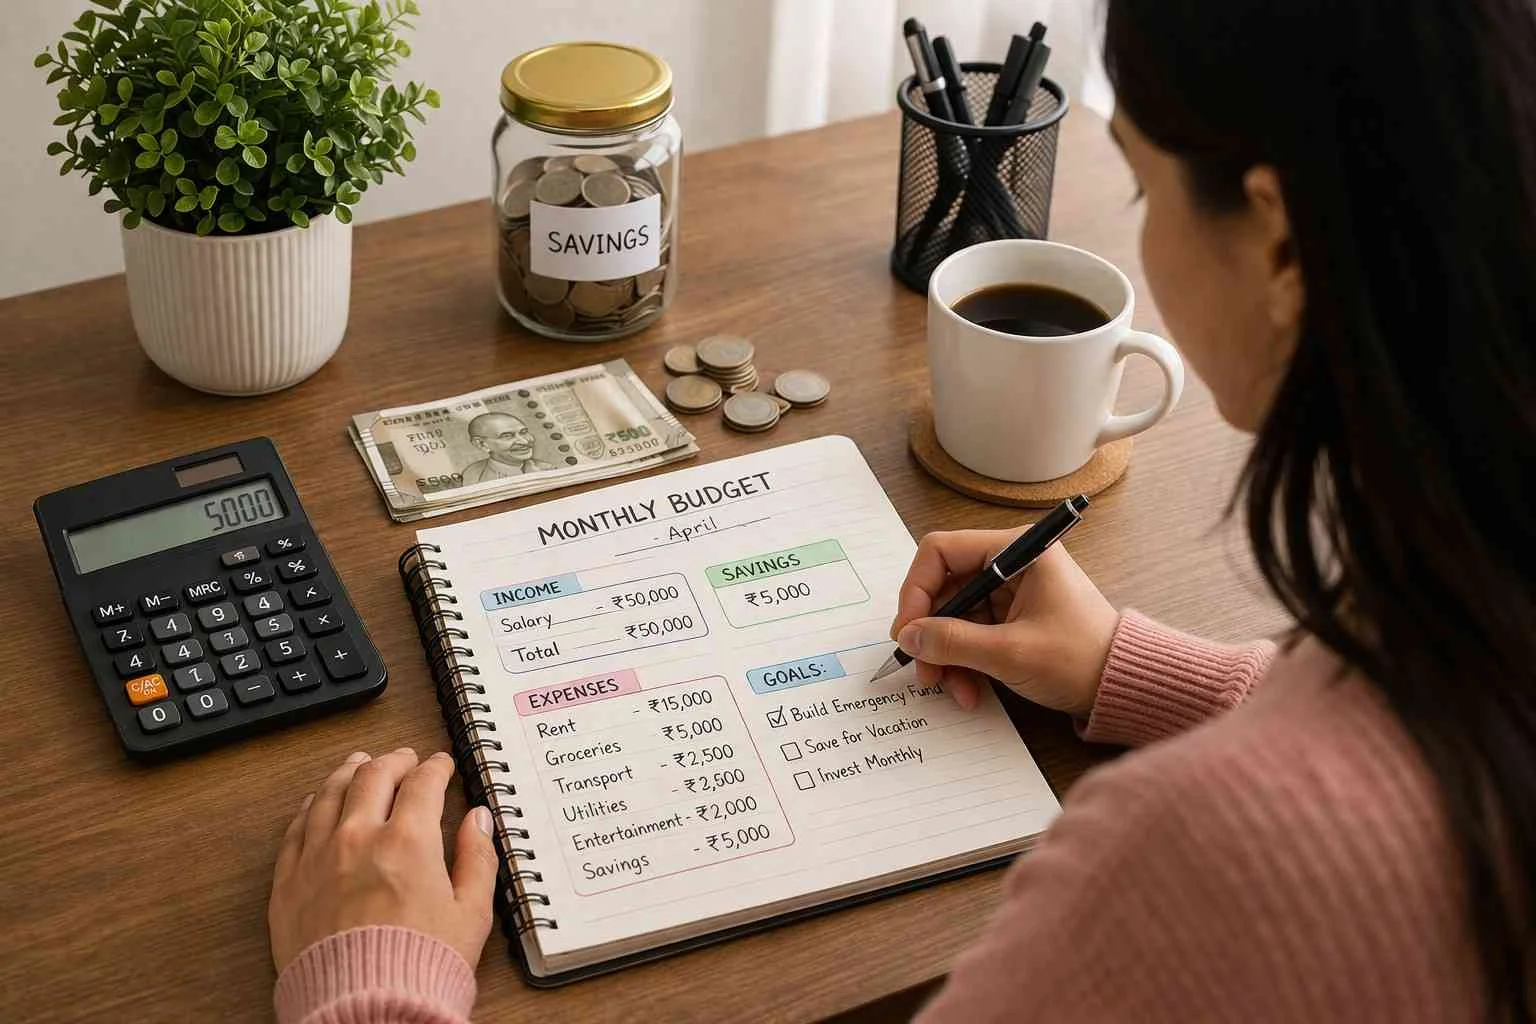
The CFPB provides a monthly budget worksheet for organizing income and spending. Be cautious with companies that promise guaranteed debt elimination or pressure you to pay large fees before clearly explaining their services.
Frequently Asked Questions
How many budget categories should I use?
Use enough categories to understand where money goes without making tracking exhausting. Many households benefit from broad categories with a few separate lines for expenses that need closer control.
Should I use the same budget every month?
Probably not exactly. Utilities, transportation, school costs, travel, holidays, and other expenses change, so monthly adjustments can make the plan more realistic.
What if my spending is higher than my income?
Start by confirming the numbers and separating essential obligations from adjustable expenses. Significant or persistent shortfalls may require expense reductions, income changes, creditor discussions, or qualified financial guidance.
Make the Numbers Match Real Life
A workable budget doesn’t punish you for spending differently from a template. It shows where your money is actually going and helps you make deliberate changes. Track several months, include irregular expenses, adjust unrealistic categories, and review the plan regularly. The more accurately your budget reflects real behavior, the more useful it becomes for deciding what to change next.
This article is for general informational purposes and is not a substitute for personalized financial advice.
Related Posts